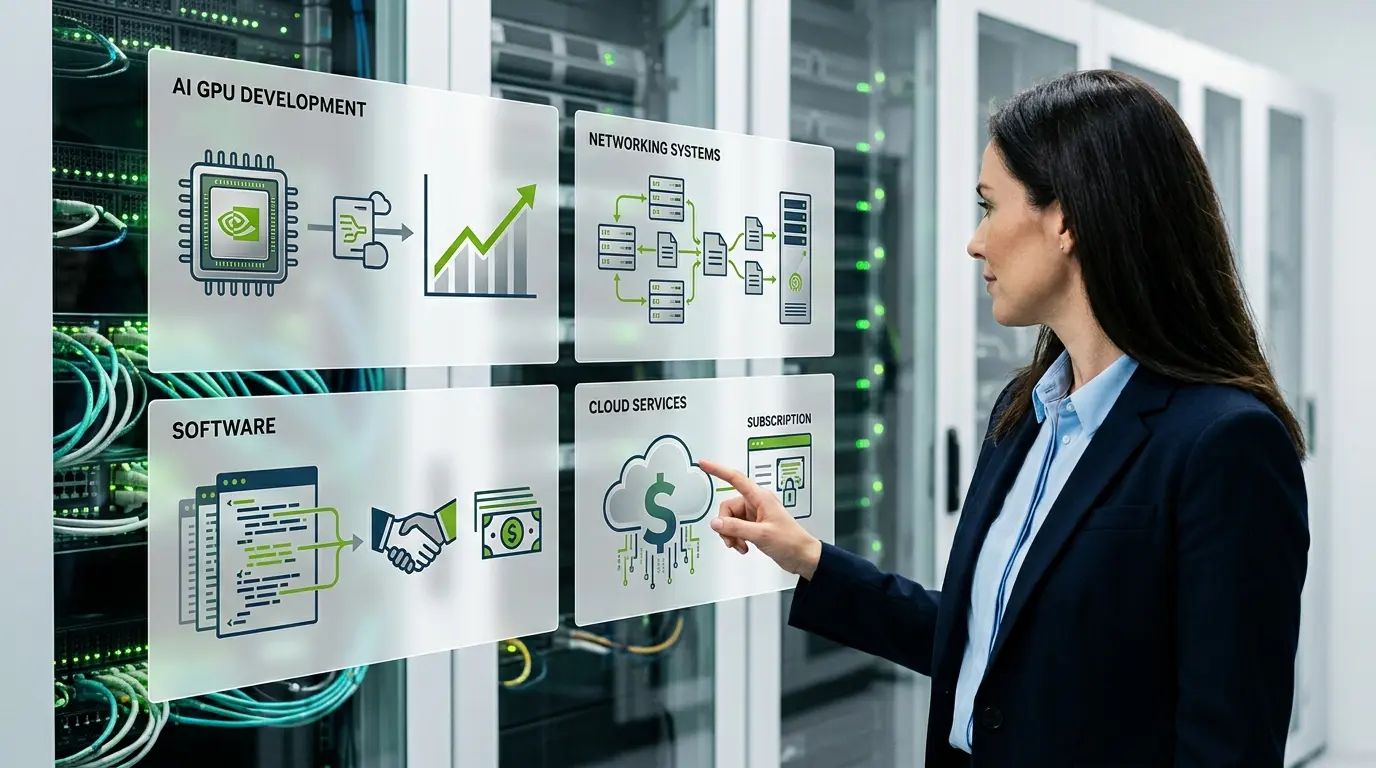
Nvidia makes most of its money from selling the computing infrastructure used to train, fine-tune and run artificial-intelligence systems. The largest revenue source is data-centre compute: GPUs and rack-scale platforms built around them. Networking, complete systems, enterprise software and support expand the amount Nvidia can earn from each deployment.
That business model is broader than “selling AI chips.” Nvidia designs processors, interconnects, switches, network adapters, systems and software, then sells them through cloud providers, server makers, contract manufacturers, distributors and direct enterprise relationships. It does not fabricate most chips in its own factories; it operates a fabless model and relies on foundries and manufacturing partners.
For Nvidia's company history and complete market portfolio, read what Nvidia does. For the technical platform behind the revenue, use our complete Nvidia AI guide. This article owns the business model, revenue mix, margins, customer concentration and financial-risk questions. It is not investment advice and does not provide a stock-price forecast.
Nvidia's AI business at a glance
| Revenue layer | What Nvidia sells | How it creates revenue |
| Data-centre compute | GPUs, accelerator modules, Grace CPUs, BlueField DPUs and related boards | Hardware sales through clouds, OEMs, ODMs, distributors and system partners |
| Networking | InfiniBand, Spectrum-X Ethernet, NVLink switches, adapters, cables and DPUs | Networking hardware and software required to connect accelerators at cluster scale |
| Systems | HGX platforms, DGX servers, NVL racks and SuperPOD designs | Higher-value integrated platforms combining multiple Nvidia components |
| Enterprise software | Nvidia AI Enterprise, vGPU, NIM, support and selected software licenses | Per-GPU subscriptions, perpetual licenses, cloud consumption and support |
| Cloud and services | DGX Cloud and partner-hosted Nvidia software routes | Cloud service, software consumption and strategic capacity arrangements |
| Edge computing | Gaming GPUs, workstations, automotive, robotics and embedded platforms | Hardware, software, development services and platform agreements outside central data centres |
| Investments and partnerships | Stakes in AI companies and strategic ecosystem agreements | Primarily ecosystem expansion and financial returns; not ordinary product revenue |
The current financial picture
Nvidia's financial year ends in late January. Fiscal year 2026 therefore covers the year ended January 25, 2026, not the calendar year 2026.
According to Nvidia's fiscal 2026 Form 10-K, total revenue reached approximately $215.9 billion, up 65% from the prior year. Data Center generated about $193.7 billion, or almost 90% of total revenue.
Fiscal year 2026 revenue by end market
| End market | FY2026 revenue | Share of total revenue | Year-over-year direction |
| Data Center | $193.737 billion | 89.7% | Up 68% |
| — Compute | $162.361 billion | 75.2% | Main AI accelerator and compute platform layer |
| — Networking | $31.376 billion | 14.5% | Expanded with AI-cluster networking demand |
| Gaming | $16.042 billion | 7.4% | Up 41% |
| Professional Visualization | $3.191 billion | 1.5% | Workstation graphics and AI workloads |
| Automotive | $2.349 billion | 1.1% | Vehicle compute and software platforms |
| OEM and Other | $619 million | 0.3% | Smaller and legacy OEM activity |
| Total | $215.938 billion | 100% | Up 65% |
Percentages are calculated from the published end-market table and rounded. They show why Nvidia is now primarily an AI-infrastructure company in financial terms, even though GeForce gaming remains an important product and brand.
First quarter fiscal 2027
Nvidia's first-quarter fiscal 2027 results, for the quarter ended April 26, 2026, reported:
| Metric | Q1 FY2027 | Change from a year earlier |
| Total revenue | $81.615 billion | Up 85% |
| Data Center revenue | $75.2 billion | Up 92% |
| Data Center compute | $60.4 billion | Up 77% |
| Data Center networking | $14.8 billion | Up 199% |
| Edge Computing | $6.4 billion | Up 29% |
| GAAP gross margin | 74.9% | Up from 60.5% |
Data Center represented roughly 92% of quarterly revenue. Under the previous sub-market presentation, compute supplied approximately 74% of total company revenue and networking approximately 18%.
AI World Today covered the quarter in Nvidia's record Q1 fiscal 2027 results.
Nvidia changed its reporting framework
Beginning with fiscal 2027, Nvidia is transitioning to two broad market platforms:
- Data Center, divided into Hyperscale and ACIE—AI Clouds, Industrial and Enterprise;
- Edge Computing, covering devices and systems for agentic and physical AI, including PCs, gaming, workstations, AI-RAN, robotics and automotive.
This change better reflects the company's current strategy, but it complicates comparisons with older reports. When updating this article, do not silently combine the new platform categories with the previous Gaming, Professional Visualization and Automotive table. Keep periods and definitions explicit.
Revenue layer 1: AI accelerators and compute platforms
The core transaction is the sale of accelerated-computing hardware.
Nvidia's data-centre compute portfolio includes:
- H100 and H200 Hopper accelerators;
- Blackwell and Blackwell Ultra GPUs;
- Grace CPUs and Grace Blackwell combinations;
- BlueField data-processing units;
- PCIe cards and accelerator modules;
- HGX server platforms;
- DGX systems;
- and NVL rack-scale platforms.
Nvidia can sell a processor or module to an OEM that builds a server. It can sell a more complete platform to an ODM, cloud provider or enterprise. The closer the product moves toward a complete rack, the more of the system's value Nvidia can potentially capture.
Why compute revenue expanded so quickly
The demand is driven by several overlapping transitions:
- frontier-model training;
- large-scale inference and reasoning;
- recommendation and advertising systems;
- enterprise generative AI;
- scientific computing;
- sovereign AI programmes;
- robotics and physical AI;
- and replacement of some CPU-only workloads with accelerated computing.
A customer does not buy an accelerator merely because “AI is growing.” It buys capacity to produce a measurable service: train a model, serve tokens, run a recommender, simulate a system or process data. Nvidia's revenue depends on those customers continuing to justify infrastructure spending.
Revenue layer 2: networking
Modern AI clusters need accelerators to exchange data at high speed. That makes networking part of the compute platform rather than an accessory.
Nvidia's networking portfolio includes:
- NVLink and NVLink switches for scale-up communication;
- InfiniBand adapters, switches and cables;
- Spectrum-X Ethernet platforms;
- BlueField DPUs;
- network software and management;
- and optical and electrical connectivity components supplied through an ecosystem.
The 2020 acquisition of Mellanox gave Nvidia an established high-performance networking business. In fiscal 2026, networking generated $31.4 billion. In the first quarter of fiscal 2027, it reached $14.8 billion and grew faster than compute year over year.
Networking matters financially for two reasons.
First, it increases Nvidia's revenue per AI deployment. A customer buying thousands of GPUs may also buy switches, adapters and interconnect technology.
Second, system performance depends on the fabric. If Nvidia can optimize chips, communication libraries and network hardware together, it can defend the value of the complete platform rather than compete on GPU specifications alone.
Revenue layer 3: complete systems and AI factories
Nvidia increasingly sells an architecture rather than a component.
A complete AI factory can include:
- GPU and CPU compute trays;
- NVLink switching;
- InfiniBand or Ethernet scale-out networking;
- BlueField infrastructure processing;
- rack design;
- software images;
- cluster management;
- and validated deployment guidance.
DGX servers, DGX SuperPOD and GB200 or GB300 NVL systems move Nvidia higher in the value chain. Even when an OEM or cloud provider sells the final system, Nvidia can supply several high-value components and the reference architecture.
For the engineering and deployment detail, read our Nvidia DGX and AI factories guide.
Why rack-scale selling changes the economics
A chip vendor is paid for the processor. A platform vendor can be paid for:
- the processor;
- interconnect and switching;
- networking adapters and switches;
- systems software;
- support;
- and sometimes cloud or enterprise software consumption.
This “attach” opportunity is a central part of Nvidia's full-stack strategy. It also increases execution risk. Rack-scale products require power, cooling, manufacturing, networking, qualification and customer facilities to arrive together. A delay in one layer can postpone revenue from the entire system.
Revenue layer 4: software and support
Nvidia's software is strategically central, but public financial reporting does not isolate a simple “CUDA revenue” line.
CUDA itself is generally provided as the developer platform around Nvidia hardware. It helps drive hardware demand and customer retention. Nvidia then monetizes selected software and support directly through products such as:
- Nvidia AI Enterprise;
- Nvidia NIM and supported production components;
- virtual GPU software;
- Omniverse enterprise and industrial software routes;
- automotive software and development services;
- and support agreements.
Nvidia's current AI Enterprise pricing lists self-managed subscriptions primarily on a per-GPU basis and cloud production consumption on a per-GPU-hour software charge, in addition to infrastructure cost.
Our Nvidia AI Enterprise guide owns the detailed component, entitlement and price tables.
Software has direct and indirect value
Direct value comes from licenses and support.
Indirect value can be larger:
- developers choose Nvidia because required libraries are available;
- organizations avoid porting costs;
- optimized software improves hardware utilization;
- a stable toolchain encourages repeat purchases;
- and applications built around CUDA can make a competitor's hardware less substitutable.
That is why the economic value of CUDA cannot be read from a software-revenue line alone.
Revenue layer 5: cloud access and services
Customers can use Nvidia infrastructure without owning it.
Nvidia GPUs are sold into Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Cloud and specialist AI-cloud providers. The cloud provider buys or finances infrastructure, then sells instances or managed services to end customers.
Nvidia also offers routes such as DGX Cloud and cloud-hosted AI Enterprise software. These can create direct service or consumption revenue and help strategic customers obtain capacity.
Cloud distribution expands the market because it lets a startup or enterprise rent accelerators by the hour instead of building a data centre. It also creates powerful customers with their own custom chips. Amazon, Google and Microsoft can be Nvidia buyers, distribution partners and competitors at the same time.
Revenue layer 6: edge computing
Not all Nvidia AI revenue is generated in hyperscale data centres.
The Edge Computing platform includes:
- GeForce and RTX GPUs for PCs and gaming;
- RTX PRO workstations and servers;
- automotive compute and DRIVE software;
- robotics platforms such as Jetson and Isaac;
- industrial simulation and Omniverse;
- AI-RAN and telecommunications;
- and embedded systems for physical AI.
The first-quarter fiscal 2027 reporting change groups these businesses around processing at the edge. The products can use the same underlying CUDA, Tensor Core and software ecosystem as data-centre offerings, creating technical reuse across markets.
Gaming remains economically meaningful. It is not accurate to describe every GeForce sale as “AI revenue,” even though AI features such as DLSS and local model acceleration increase the product's value. Keep end markets distinct when interpreting Nvidia's financials.
Who pays Nvidia?
Nvidia's end users include cloud providers, AI laboratories, internet companies, enterprises, governments, universities, carmakers and industrial companies. The direct invoice may go to a different party.
Direct customers can include:
- original equipment manufacturers;
- original design manufacturers;
- contract manufacturers;
- system integrators;
- distributors;
- and cloud-service providers.
A Taiwan-headquartered manufacturer may assemble systems for an end customer in the United States or Europe. Nvidia's geographic revenue by direct customer headquarters therefore does not necessarily show where the final AI capacity is used.
Customer concentration
Nvidia's scale is accompanied by significant customer concentration.
The fiscal 2026 10-K states that:
- one direct customer represented 22% of total revenue;
- another represented 14%;
- both were primarily associated with Compute & Networking.
The customers were not named in that disclosure. Do not infer or publish identities as fact without a separate authoritative source.
Concentration can be efficient because a small number of cloud providers and system partners deploy enormous quantities of infrastructure. It creates risk if one customer changes architecture, slows capital spending, develops a custom chip or shifts procurement to a competitor.
Why Nvidia's gross margins are high
Nvidia reported a 74.9% GAAP gross margin in Q1 fiscal 2027. That is company-wide gross margin, not the margin on one H100, rack or software license.
Several factors can support high margins:
High-value intellectual property
Nvidia sells designs, systems architecture and software rather than commodity silicon alone. Customers pay for delivered performance, ecosystem and time to market.
Fabless manufacturing
Nvidia relies on foundries and manufacturing partners instead of owning the complete fabrication network. This reduces the capital intensity of building leading-edge fabs, although Nvidia still commits substantial money to supply and capacity.
Scarce capacity and strong demand
When customer demand exceeds deliverable supply, pricing and product mix can be favorable. That condition is not permanent by definition.
System and networking attach
A deployment can contain several Nvidia products, increasing total value per installation.
Software leverage
A large body of software can support multiple hardware generations and customers. Nvidia's 10-K says more than half of its engineers work on software, showing that the “fabless” model is not a low-research model.
Margins can decline when supply costs rise, demand changes, competition increases, export restrictions create inventory charges or a new product transition has higher initial costs.
The fabless model
Nvidia designs products but relies on outside companies for manufacturing.
Its 2026 10-K names:
- TSMC and Samsung as wafer foundries;
- SK Hynix, Micron and Samsung as memory suppliers;
- CoWoS for advanced packaging;
- Hon Hai, Wistron and Fabrinet among assembly, testing and packaging partners.
This model lets Nvidia concentrate capital and staff on architecture, software and systems. It also makes the company dependent on scarce leading-edge fabrication, HBM, packaging and manufacturing capacity.
Our separate guide maps the complete Nvidia and TSMC AI chip supply chain.
Product cadence and revenue timing
Nvidia has moved toward an annual data-centre platform cadence. Faster releases can increase performance and maintain leadership. They also make revenue more volatile.
A platform transition can create:
- customers delaying orders for the next generation;
- partners reducing prior-generation inventory;
- overlapping old and new products;
- qualification delays;
- manufacturing complexity;
- and facility-readiness problems for denser systems.
Blackwell represented the majority of Data Center revenue in fiscal 2026, according to the 10-K. Rubin is the next transition. The financial result depends not only on whether the chip works, but whether memory, packaging, racks, cooling and customer sites are ready.
Capital commitments and working capital
A fabless company can still commit enormous capital.
Nvidia may make non-cancellable purchase commitments for wafers, memory, packaging, components, manufacturing and cloud or data-centre capacity. It also carries inventory and accounts receivable while systems move through partners.
The business therefore has several timing risks:
- demand can change after capacity is reserved;
- a product can become restricted before sale;
- a customer can delay a data centre;
- a new architecture can make older inventory less desirable;
- and supplier constraints can leave one missing component holding back a complete rack.
High reported demand does not remove supply-chain or working-capital execution.
Investments in AI companies
Nvidia also invests in AI laboratories, cloud providers and software companies. Those investments can:
- expand the customer ecosystem;
- encourage workloads optimized for Nvidia;
- secure strategic relationships;
- support new markets;
- and generate financial gains or losses.
They should not be confused with ordinary product revenue. In Q1 fiscal 2027, Nvidia reported a large net gain in other income related to equity securities. That helped net income, but it is economically different from selling GPUs or networking.
AI World Today's coverage of Nvidia's investment in Ilya Sutskever's Safe Superintelligence illustrates the ecosystem strategy.
Nvidia's biggest business risks
AI capital spending slows
A large share of revenue depends on continued infrastructure spending by a relatively concentrated group of customers.
Customers build custom chips
Google, Amazon, Microsoft and other large customers design their own accelerators. Custom silicon can replace Nvidia in selected workloads or improve negotiating leverage.
AMD and other competitors improve
AMD, Huawei, Intel and specialist architectures can compete on price, memory, openness, regional availability or workload specialization. Read our full Nvidia competitors guide.
Export controls and China
Nvidia's Q2 fiscal 2027 outlook assumed no Data Center compute revenue from China. Export restrictions can remove markets, create inventory charges, complicate support and accelerate domestic alternatives.
Supply concentration
Leading-edge foundry, HBM and advanced-packaging capacity are concentrated among a small number of suppliers and regions.
Product transitions fail or arrive late
A processor, switch, board, cooling design or software stack can delay the complete platform.
Power and data-centre constraints
Customers may want accelerators but lack electricity, cooling, transformers, network capacity or a permitted site.
Software becomes more portable
Framework improvements, open standards and compiler layers can reduce switching costs. Nvidia's software advantage must be maintained rather than assumed.
Pricing pressure
Competitors or custom chips can force lower prices. Customers can also optimize models to use fewer accelerators per unit of output.
How to evaluate the durability of Nvidia's AI business
Do not judge the business from one quarter or one GPU benchmark. Track:
- Data Center compute growth.
- Networking growth and attach.
- Product availability versus announcements.
- Gross margin through transitions.
- Customer concentration.
- Software and support adoption.
- Cloud and OEM inventory.
- Supply commitments and inventory charges.
- Export-control impact.
- Customer cost per useful AI output.
The final measure is whether customers continue to earn enough from AI services to buy the next generation of infrastructure.
Common interpretation mistakes
Calling all Nvidia revenue AI revenue
Gaming, workstation and automotive revenue can use AI technology but should not automatically be relabelled as data-centre AI revenue.
Treating Data Center revenue as GPUs only
It includes compute and networking platforms, systems, AI solutions and software.
Treating a run rate as reported annual revenue
A current annualized pace is not the same as revenue earned during a completed fiscal year.
Mixing fiscal and calendar years
Nvidia fiscal 2026 ended in January 2026.
Inferring named customers from concentration percentages
The 10-K reports percentages without naming the two largest direct customers.
Treating net income as purely operating profit
Investment gains and other income can materially affect a quarter.
Using market capitalization as company revenue
Stock-market value and sales are different measures.
Assuming fabless means supply-light
Nvidia still depends on large external manufacturing commitments and scarce capacity.
Frequently asked questions
How does Nvidia make money from AI?
Primarily by selling data-centre compute and networking platforms: GPUs, accelerator modules, systems, NVLink, InfiniBand, Ethernet and related products. It also sells enterprise software, support and cloud services.
What percentage of Nvidia revenue comes from data centres?
In fiscal 2026, Data Center generated approximately 89.7% of total revenue. In Q1 fiscal 2027, it represented about 92%.
Does Nvidia make money from CUDA?
CUDA drives hardware demand and platform loyalty. Nvidia also sells paid software built around its ecosystem, but public reporting does not provide one separate “CUDA revenue” figure.
Does Nvidia manufacture its own chips?
Nvidia is primarily fabless. It designs products and uses foundries such as TSMC and Samsung, memory suppliers and contract manufacturers.
Who buys Nvidia AI chips?
Cloud providers, AI laboratories, internet companies, enterprises, governments and research organizations use them. Direct customers can be OEMs, ODMs, distributors, integrators and cloud providers.
How much revenue did Nvidia report in fiscal 2026?
Approximately $215.9 billion. Data Center contributed $193.7 billion.
How much did Nvidia earn from networking?
Fiscal 2026 Data Center networking revenue was approximately $31.4 billion. Q1 fiscal 2027 networking revenue was $14.8 billion under the previous sub-market presentation.
Why are Nvidia's margins high?
Nvidia sells differentiated architecture, software and systems into strong demand through a fabless model. Product mix, scarcity and platform integration can support margins, but the exact drivers vary by period.
Is Nvidia a hardware or software company?
Both, plus systems and services. Most reported revenue comes through hardware-heavy platforms, while software is central to product performance, differentiation and customer retention.
Is this article investment advice?
No. It explains the operating business and reported financials. A security's value also depends on expectations, price, risk and an investor's circumstances.
Bottom line
Nvidia's AI business is a layered platform model. Compute supplies the largest revenue pool. Networking and rack-scale systems increase the value captured per deployment. CUDA and enterprise software make the hardware more useful and harder to replace. Clouds, OEMs and manufacturing partners distribute the platform globally.
The same concentration that creates extraordinary scale creates risk. Nvidia depends on major customers, external manufacturing, continued AI capital spending, successful product transitions and access to global markets. The business remains strongest when customers can convert Nvidia infrastructure into useful, repeatable output at an economic cost.

byDavid Porter
Popular news

Anthropic Researchers Warn Advanced AI Models Could Trigger Human Extinction

Senator Josh Hawley Launches Massive Investigation Into OpenAI After Critical Hugging Face Breach

Andy Burnham Faces Urgent Demands to Block Artificial Superintelligence in Manchester

UK Computer Science Graduates Face a Massive Job Market Shift Driven by AI

Anthropic Researchers Issue Urgent Warning Regarding Elon Musk and Global AI Safety Risks

OpenAI Board Member Paul Christiano Warns AI Control Could Be Lost Forever
Latest comments
Loading