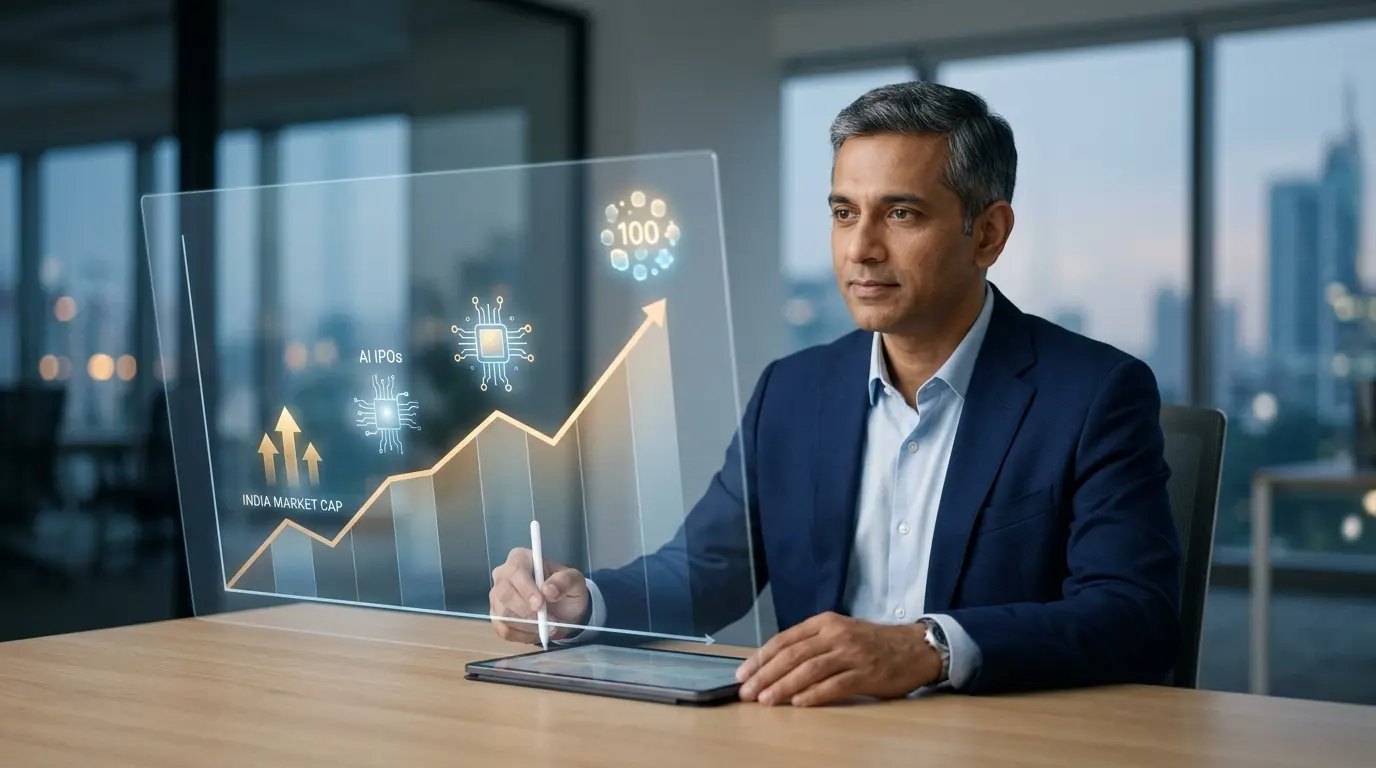
India’s emerging artificial intelligence ecosystem is poised for a massive transformation. A recent analysis by Goldman Sachs indicates that artificial intelligence driven initial public offerings could add between 50 billion and 100 billion dollars to the national listed market capitalization over the next two to five years. This projection highlights a significant shift as private technology firms prepare to enter the public markets.
The investment bank estimates that 25 to 50 percent of nearly 70 mid to late stage private artificial intelligence companies might go public during this timeframe. These listings would occur at a weighted average valuation roughly four times their current estimated value. Timothy Moe, co head of Asia macro research and chief Asia Pacific equity strategist at Goldman Sachs, noted that these public debuts would broaden the listed artificial intelligence universe. You can explore the broader economic implications of such technological shifts through the Stanford University AI Index Report, which tracks global artificial intelligence development and investment trends.
Private equity funding for Indian artificial intelligence startups has tripled since 2024. The share of artificial intelligence in total private equity allocations has quadrupled to approximately one fifth of all private capital deployed in the country. India now ranks among the top six global destinations for private artificial intelligence funding. This challenges the outdated perception that the nation remains on the periphery of the global technology buildout.
Goldman Sachs identified 84 private companies as Private AI Contenders. These entities hold an estimated combined current value of 55 billion dollars. They account for nearly 40 percent of all artificial intelligence related private capital raised in India since 2025. The cohort spans the entire value chain from infrastructure providers to businesses deploying artificial intelligence across various industries. The breakdown of these contenders reveals distinct market dynamics.
| Market Segment | Number of Companies | Estimated Current Value | Projected IPO Contribution |
| Upstream Enablers | Not specified | 35 billion USD | 66 percent |
| Downstream Adopters | 42 entities | 18 billion USD | 31 percent |
| Midstream Core Developers | 7 entities | 2 billion USD | 3 percent |
| Total Identified Contenders | 84 entities | 55 billion USD | 100 percent |
Upstream enablers represent the largest segment by financial value. This category includes companies involved in power generation, semiconductor supply chains, chip design, quantum computing, data centers, cloud services and data management. Regulatory frameworks governing these public offerings are strictly monitored by the Securities and Exchange Board of India to ensure market transparency and investor protection.
Downstream adopters form the largest group by sheer volume. These businesses apply technology across computer vision, conversational systems, robotics, edge computing, healthcare, financial services, enterprise software, defense, cybersecurity and commerce.
The midstream segment remains relatively small. It comprises core developers engaged in foundational research, model training and operational management.
While these projected additions might seem modest compared to the 670 billion dollar listed enablers universe identified in earlier analyses, the broader significance lies in ecosystem expansion. Potential initial public offerings could introduce currently underrepresented businesses to public investors. These include data center operators, enterprise services, cloud providers, healthcare technology companies and computer vision specialists. The companies are concentrated in established technology hubs led by Bengaluru, Delhi NCR, Mumbai and Hyderabad, with Ahmedabad, Pune and Chennai emerging as additional centers of activity.
byDavid Porter
Popular news
Anthropic’s $80.7 Billion Loss Explained in Today’s AI News Podcast
AI breathes new life into an old game: ask for your own Fallout 2 mods
Microsoft wants to keep AI agents in the workplace on a tighter leash
AI Cleans Up Your TV with CleanYourTV
Global Memory Shortage Threatens Corporate AI Adoption
Australian Federal Police Warns of AI Accelerated Youth Radicalization Risks
Latest comments
Loading